Client, stolen-vehicle total loss · Stolen vehicle, total loss · 2017 Subaru Outback Touring
+$4,552after the client came to us
First offer $10,821. The client got it to $14,798 on her own before hiring us, so we count only the increase after that.
Lowball settlement offers
Your insurer has an algorithm. You get the comparable sales and a documented valuation to answer it.
Upload your insurer's valuation report
The CCC or Mitchell report from your insurer. We read it and tell you plainly whether the offer holds up. Free.
Upload your CCC ONE report
PDF, photo, or text — tap to choose, or drag it here
No report yet? Start here instead.
Was your car totaled or repaired?
We calculate your estimate differently depending on what happened.
We use your document only to calculate your estimate. We do not share or sell your information.
Your insurer's report. Your evidence. Your money.
After an accident, carriers use their own tools to minimize what they owe you. We read those numbers and show you what a fair recovery could look like.
Your insurer's valuation report is usually a PDF titled something like "Total Loss Valuation" or "Vehicle Valuation Report" from CCC or Mitchell. It's in your settlement packet, or you can request it from your adjuster.
Diminished value is the gap between what your car was worth before the accident and after, even once repairs are done. You can seek it from an at-fault driver's insurer as part of a liability claim. This is a recognized claim type, not a loophole. We are not your attorney and this is not legal advice.
Reports reviewed and signed by an ASCAA Certified Auto Appraiser (Certificate ASCAA-CERT-9659)
See a sample appraisal report — PDF, 51 pages
Documented results
Our first closed paid case, measured from the offer the client had when they came to us. 1 closed so far; 3 more are still open, and we add results here as they close.
Client, stolen-vehicle total loss · Stolen vehicle, total loss · 2017 Subaru Outback Touring
First offer $10,821. The client got it to $14,798 on her own before hiring us, so we count only the increase after that.
A Bay Area client, coached at no charge · Total loss · 2017 Chevrolet Silverado 3500HD
Referred by her body shop. We produced no document: we advised by text and email on comps, her written response and the appraisal clause, and checked the settlement breakdown. The insurer's first offer was $40,916 and its own appraiser later said $34,970; she negotiated the $43,000 herself (10/13/2026). No kit was purchased. Not counted in paid-customer figures.
I was skeptical how this would all work when I first contacted [us] but I have been pleasantly surprised. The process has been easier and faster than I imagined, no doubt due to your diligence and quick responses to all my questions and requests. I am extremely satisfied with your work and the settlement that you were able to generate for our stolen vehicle.
Zoheb was amazing. I couldn't have done this without his guidance. … His communication was great any time I had a question or needed his assistance he was on top of it. Thank again Zoheb for all your help. We greatly appreciate you.
Where this started: our founder’s own family car. The insurer said $17,262; the paperwork got it to $29,155 in writing, $11,643 more like for like. Not a client result, and not counted above.
Results vary. Every claim is different, and some recover less or nothing above the insurer's offer. Not legal advice. Figures come from each claim’s own documents.
Why us
$249 or $349, once, and you keep every dollar you recover. Recover under $500 with the Full Claim Kit and we refund the $349.
We check their CCC or Mitchell valuation line by line against live comparable listings, so your answer is built on their numbers. That first check is free.
An appraisal signed by an ASCAA Certified Auto Appraiser and a demand letter already written in your name, about 2 business days after we have your documents. Fully remote: you upload, read and send.
What each option would cost you on an example $5,000 increase. Illustration only, not a quote from any firm, and many won’t take a claim this size.
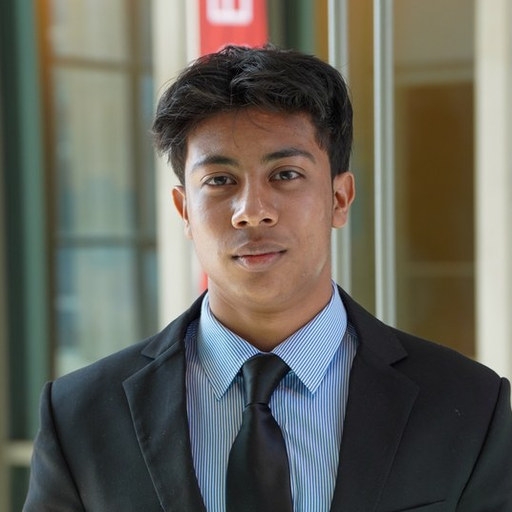
Zoheb Alvi, Co-founder & CEO
 Indiana University Alum
ASCAA Certified Auto Appraiser (Certificate ASCAA-CERT-9659). He reviews and signs every valuation report before it goes out.
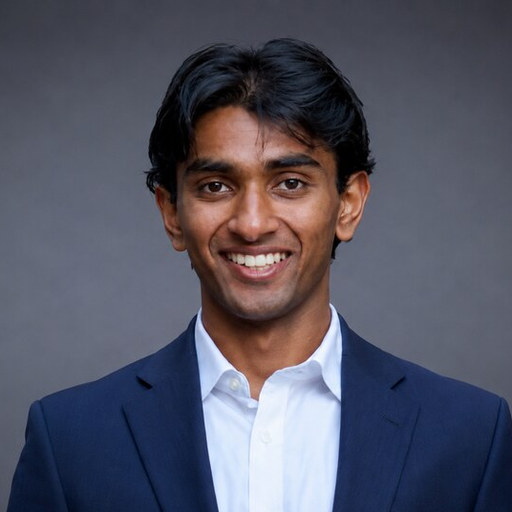
Ajay Donthula, Co-founder & COO
 Princeton University
Leads engineering.
How it works
Free, right now
Upload the insurer's valuation report, a PDF or a photo. We read it and tell you plainly whether the number holds up. No account, no card.
About 2 business days
If it's worth answering, pick a kit. About 2 business days after we have your documents, you get the evidence and a demand letter already written in your name. Full Claim Kit appraisals are signed by an ASCAA Certified Auto Appraiser.
You stay in control
You email the letter to your adjuster, or sign a one-page authorization and we send it for you. Forward whatever they reply and we tell you how to answer.
Check before you sign. Accepting the offer and signing the insurer’s release usually closes the claim, and with it your chance to ask for more.
Pricing
Start with the free check. Pay only if you decide the claim is worth answering.
Your car was totaled
$349
Once, per claim. Or 4 payments at checkout.
Recover under $500? We refund the $349. Terms (not offered in Florida).
Your car was repaired
$249
Once, per claim.
What’s in the kits
Prove the number
Make the demand
Stay on track
Questions
Made whole means that after a covered loss, you should be restored to the same financial position you were in before the incident — no better, no worse. In a total-loss claim, that means receiving the fair market value of your vehicle before the accident.
The principle of indemnity and made-whole doctrine appear in both insurance law and policy language, but the specific rights available to you depend on your state, your policy, and the facts of your claim. An appraisal clause in your policy is the most common enforcement mechanism short of litigation.
An appraisal clause is a provision in most auto policies that allows either party — you or the insurer — to demand an independent appraisal when there is a disagreement about the value of a vehicle. Each side selects their own appraiser; if the two appraisers disagree, a neutral umpire decides.
In most states, a properly completed appraisal process results in a binding award. Your insurer is required to pay the appraised amount even if it is higher than their original offer.
If you signed a release of liability, your options may be limited depending on the language of the release and your state's laws. If you have not signed, you still have options — and we can help you evaluate them.
It’s free and takes a couple of minutes. You’ll know whether the number holds up.
Reports reviewed and signed by an ASCAA Certified Auto Appraiser (Certificate ASCAA-CERT-9659). Not a law firm or a public adjuster; not legal advice.